
High-net-worth advisory firms provide coordinated, specialist services aimed at managing complex financial situations for individuals and families with substantial assets. These firms typically combine investment management, tax and estate planning, risk assessment, and administrative support to address multiple objectives such as capital preservation, intergenerational wealth transfer, liquidity for life events, and tailored income needs. Teams often include portfolio managers, tax professionals, estate planners, and specialists for alternative assets, enabling integrated solutions that respond to varied legal, fiscal, and personal constraints. The focus is on aligning asset strategies with long-term goals while accommodating unique liability, tax, and legacy considerations.
Such firms may operate under different engagement models, including discretionary mandates where managers implement decisions within agreed parameters, and advisory arrangements that require client approval for significant changes. Services can be delivered by multi-family offices, single-family offices, or specialist teams within larger financial institutions; each model typically differs in scale, governance, and scope of non-investment services. Coordination across disciplines is often a distinguishing feature: investment choices may be adjusted in response to estate-planning decisions, and liquidity planning may influence asset allocation. Confidentiality, documentation, and compliance processes are commonly emphasized in these relationships.
Discretionary investment management usually centers on establishing an investment policy statement that defines objectives, risk tolerances, allowable asset classes, and liquidity constraints. Portfolio managers may implement diversified allocations across equities, fixed income, real estate, private equity, and hedge funds to pursue risk-adjusted outcomes. Decision protocols can include regular rebalancing, overlay strategies for currency or interest-rate exposure, and periodic reviews tied to life events. Where private assets are included, timelines for capital calls and distributions are typically factored into overall liquidity planning. Clients may receive periodic performance and compliance reporting linked to the policy statement.
Family office and administrative services often extend beyond pure investment oversight to include operational coordination that reduces fragmentation across providers. Typical functions include consolidated reporting, bill and cash-flow management, coordination of multiple custodians, and facilitation of estate-administration tasks. Multi-generational governance frameworks may be established to guide decision-making, define roles, and document investment and philanthropic principles. In some models, family offices also evaluate service providers and centralize negotiations for banking, insurance, and legal services, aiming to achieve administrative clarity rather than prescribe particular solutions.
Tax and estate planning coordination commonly involves iterative conversations among portfolio managers, tax specialists, and legal advisors to align asset location, gifting strategies, and trust structures with investment objectives. Tax-efficient investment choices may include tax-loss harvesting, holding period considerations, and selection of tax-exempt vehicles where appropriate. Estate planning techniques such as trusts, life insurance structures for liquidity, and powers of attorney are often evaluated alongside investment liquidity to ensure that settlement or transfer events can be supported without forced asset sales. Documentation and periodic reviews are typically used to keep plans current with changing laws and family circumstances.
Risk management and diversification strategies are applied across the asset mix and operational practices. Risk assessment may include scenario analysis for market shocks, concentration risk reviews when a meaningful proportion of net worth resides in a single asset or business interest, and stress testing of cash-flow plans. Diversification may be pursued through allocation to different sectors, geographies, and return drivers, and through alternatives that have distinct correlation profiles. Operational risk controls—such as custodian segregation of assets, counterparty assessments, and documented approval workflows—are often implemented alongside investment risk measures.
In summary, high-net-worth advisory firms coordinate a range of services—investment execution, administrative consolidation, and tax and estate planning—to address complex portfolios and long-term objectives. The models and specific tools used can vary substantially depending on preferences for discretionary authority, desired operational scope, and the nature of assets involved. These integrated approaches may help align liquidity plans, legacy goals, and risk tolerances, while requiring ongoing governance and review. The next sections examine practical components and considerations in more detail.
Investment management in the context of complex portfolios typically begins with an articulated investment policy that sets return objectives, acceptable risk levels, and constraints such as liquidity needs or concentration limits. Asset allocation may combine public equities and fixed income with private equity, real assets, and hedge strategies to pursue diversification across return streams. Managers often evaluate correlation matrices and scenario outcomes to understand how holdings behave under stress. Where significant illiquid holdings exist, allocation decisions may be adjusted to preserve necessary cash buffers. Regular policy reviews may be used to adapt to changing market conditions or family objectives.
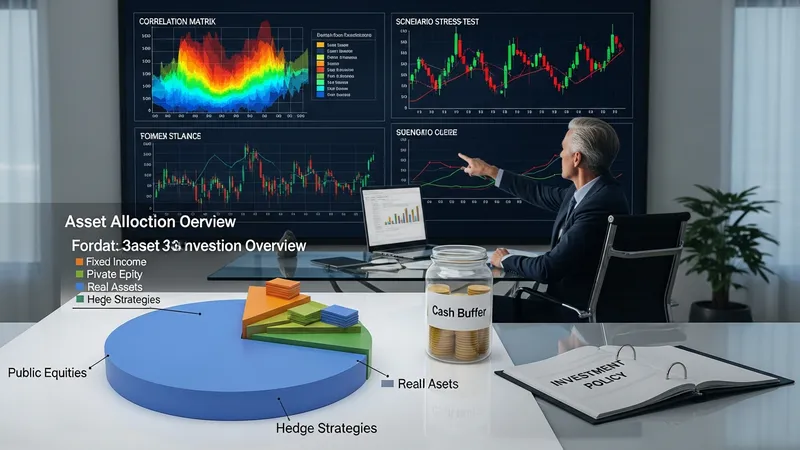
Discretionary mandates can streamline decision-making by allowing delegated portfolio managers to act within agreed parameters; advisory mandates retain client approval for major changes. Delegation may be useful when rapid market responses are required, while advisory models can be preferable where family governance demands higher oversight. Fee arrangements typically vary by model and by the inclusion of alternatives; advisory fees may sometimes be expressed as a percentage of assets under management, or as fixed or performance-linked components. Transparency in fee composition and conflicts of interest is commonly emphasized as part of governance.
Incorporating private markets often requires explicit planning for capital calls, valuation practices, and expected liquidity timelines. Private equity and real estate can offer diversification benefits but may introduce valuation variability and longer holding periods. Managers may implement pacing strategies and capital allocation buffers to accommodate these dynamics. Public-market exposure can be managed through active, passive, or blended approaches depending on cost considerations and desired risk exposures. Tax implications of turnover and the timing of realizations may also inform trading and allocation decisions.
Ongoing monitoring typically includes periodic performance measurement against benchmarks, attribution analyses, and stress tests focused on downside scenarios. Reporting systems may consolidate positions across custodians for a single view of exposure and performance. Where family offices or multi-advisor structures are used, an independent review function or external audit of portfolio processes may be enacted to provide additional oversight. Such practices are framed as tools to maintain alignment between investment implementation and documented objectives without implying outcomes.
Tax planning within comprehensive advisory relationships often seeks to integrate investment choices with tax efficiency and future transfer objectives. Advisors may evaluate tax-loss harvesting, placement of income-generating assets in tax-advantaged accounts, and the timing of capital events to mitigate tax impact. For clients with varied income sources or cross-border considerations, coordinated analysis with tax counsel may be used to identify filing requirements and reporting obligations. Periodic reviews can adapt strategies to changes in tax law or personal circumstances, noting that outcomes may vary depending on jurisdiction and specific facts.
Estate coordination typically involves aligning wills, trusts, and succession documents with investment and liquidity plans to ensure that settlement obligations can be met without forced disposals. Trust structures may be considered to manage control, tax outcomes, and asset protection within legal constraints. Life insurance is sometimes discussed as a liquidity tool to cover estate settlement taxes or provide equalization among heirs when assets are illiquid. Documentation practices and nominee arrangements are often part of broader efforts to maintain clarity and reduce administrative friction at the time of transfer.
Coordination among professionals is often central to implementing tax and estate measures alongside investment management. Legal counsel, accountants, and trustees commonly collaborate with portfolio managers to sequence actions in a tax-aware manner. For example, planned gifting or trust funding may prompt portfolio rebalancing to avoid concentrated positions. Regular communication protocols, shared reporting, and documented decision logs can reduce the risk of conflicting actions. Such coordination is framed as a process to align objectives rather than a prescriptive formula.
Regulatory and compliance considerations influence tax and estate planning choices; advisors typically emphasize documentation, timely filings, and awareness of reporting thresholds that may apply to certain assets or accounts. Periodic reviews of legal documents and beneficiary designations are often recommended to ensure consistency with current wishes and regulatory changes. Because the effectiveness of particular techniques depends on individual circumstances, outcomes are typically described as contingent on the interplay of law, asset composition, and family objectives.
Risk management in complex portfolios often entails both market and non-market assessments: market risks such as volatility and correlation shifts, and non-market risks including concentration in a closely held business or counterparty exposure. Quantitative tools—volatility measures, value-at-risk, and stress testing—may be supplemented by qualitative reviews of operational and reputational risks. Where significant concentrated positions exist, hedging strategies or gradual diversification plans can be considered, taking into account taxation and liquidity constraints. Such measures are typically presented as options that may mitigate certain exposures under particular scenarios.
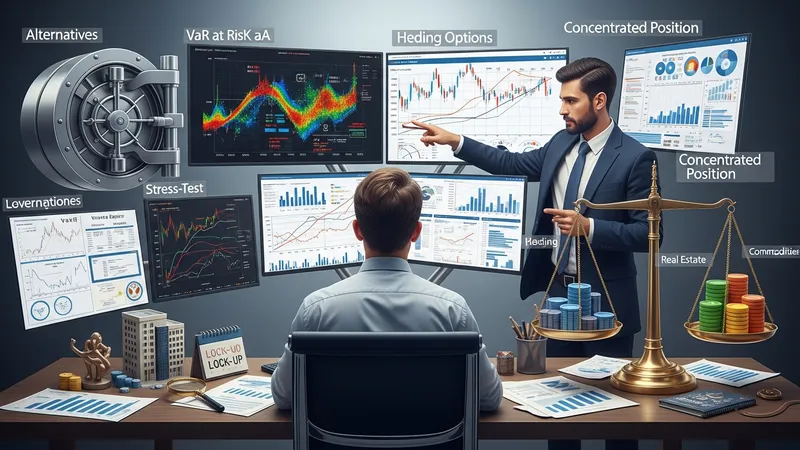
Diversification is commonly pursued across asset classes, sectors, geography, and return drivers to reduce reliance on any single source of return. Alternative assets may be included for their potential to offer distinct correlation patterns, though they can introduce complexity such as limited transparency, valuation subjectivity, and longer lock-up periods. Allocation to alternatives typically requires specific governance and monitoring practices, including clarity on fee structures, redemption terms, and reporting frequency. The decision to include alternatives often balances expected risk-return characteristics against operational implications.
Operational risk controls are an important complement to market-oriented risk management. Practices such as segregation of custody, multi-signature approvals for large transfers, and independent valuation processes for illiquid holdings are commonly used to reduce operational vulnerabilities. Counterparty due diligence and insurance reviews may also be part of standard protocols. These controls are framed as elements that can reduce certain categories of operational loss or error while acknowledging that no control can eliminate all forms of risk.
Periodic review cycles for risk frameworks are commonly established to reassess exposures as market conditions and family circumstances change. Scenario planning exercises—such as liquidity stress scenarios or succession-related events—can help clarify potential impacts and predefine response pathways. Documentation of governance decisions and contingency plans is often maintained to support orderly execution if adverse events occur. These practices serve to align risk posture with documented objectives and capacity for loss, without implying specific outcomes.
Governance arrangements are frequently tailored to family preferences, ranging from formal advisory boards to documented investment committees that set policy and approve major actions. Clear role definitions and decision-making authorities can reduce disputes and ensure continuity across generations. Governance documents commonly specify meeting cadences, reporting standards, and escalation pathways for material decisions. When multiple service providers are engaged, a central coordinator—such as a family office or chief investment officer—may facilitate information flow and record keeping to maintain consistent application of agreed principles.
Reporting practices aim to provide consolidated views of assets, liabilities, and performance across custodians and asset types. Consolidated statements often include position-level detail, cash flows, and attribution analyses, adjusted for private asset valuations as appropriate. Frequency and granularity of reporting can vary according to client needs; some prefer monthly dashboards while others opt for quarterly deep-dives. Transparency about valuation methodologies, fees, and any related-party arrangements is commonly emphasized to support informed governance.
Fee structures for comprehensive advisory services may combine asset-based fees, fixed retainers, and project-based charges depending on service scope. Advisory fees expressed as a percentage of assets under management are often cited as a typical approach, with ranges that may vary by institution and the inclusion of alternative investments. Some models separate custody and transaction costs from advisory fees to clarify cost drivers. Disclosure of fee allocation and potential conflicts of interest is typically part of standard practice to support client oversight and decision-making.
Selection criteria for advisors generally focus on demonstrated process, governance compatibility, transparency, and documented controls. Due diligence commonly includes review of investment processes, compliance programs, references, and service model fit relative to family objectives. Periodic reviews of service providers and governance arrangements may be scheduled to ensure continued alignment as objectives or market conditions evolve. These considerations are presented as factors to assess rather than prescriptive endorsements of any particular approach.